VA Loans: Review Eligibility Before You Offer
VA loans can support a home purchase with no monthly mortgage insurance. Review eligibility, payment, and funding fees before making an offer.
Why VA loans deserve a full financing review
Can a buyer use VA loans without reviewing the full payment and still make a confident offer? That approach can create surprises later. A VA loan may offer a path to homeownership with no down payment for eligible borrowers, and VA loans generally do not require monthly mortgage insurance. Those are meaningful features, although they are only part of the financing picture.
A sound review starts before an offer is written. Eligibility, available entitlement, income, credit, property standards, assets, estimated closing costs, and the complete monthly housing payment can all affect the structure of a loan. A low down payment does not remove the need for a careful budget.
Consider a buyer comparing two homes with similar prices. One property may have higher taxes, a larger insurance premium, or homeowner association dues. The interest rate could look similar on paper while the actual monthly obligation looks very different. That difference belongs in the decision before a contract is signed.
VA loans are designed to support eligible service members, veterans, and qualifying surviving spouses. Approval still depends on the borrower and the property meeting applicable requirements. John Naccarato encourages buyers to treat the VA loan review as part of their buying strategy, rather than a box to check after finding a home.
There is plenty of online advice that frames a VA loan as a simple zero-down option. The internet version leaves out the payment review, documentation, and property side of the transaction. Those details matter.
Confirm VA loan eligibility and entitlement early
VA loan eligibility begins with the Certificate of Eligibility, often called the COE. This document helps confirm a borrower's eligibility for the VA home loan benefit and may show information related to entitlement. It is a starting point for the lender's review, not a guarantee of final approval.
Available entitlement can matter when a borrower has used a VA loan before, owns another property financed with a VA loan, or is restoring entitlement after a prior transaction. A borrower should not assume prior VA loan use prevents another purchase. The available options depend on the individual file and current program requirements.
Service documentation belongs near the start
Gathering service documentation early gives the lender time to identify what is needed for the COE request or review. A buyer who waits until an offer is accepted may create an avoidable documentation scramble. Nobody needs extra paperwork during escrow if it can be addressed sooner.
For example, a buyer who previously purchased a home using VA financing may need a closer look at available entitlement before deciding how much home to shop for. That review may affect the financing structure or cash requirements. It does not mean the purchase cannot work. It means the answer should come from the actual file.
Buyers can also review their preparation with a mortgage learning center before meeting with a lender. A conversation with a loan professional can clarify which documents are relevant to the borrower's current situation.
Compare the complete VA loan payment
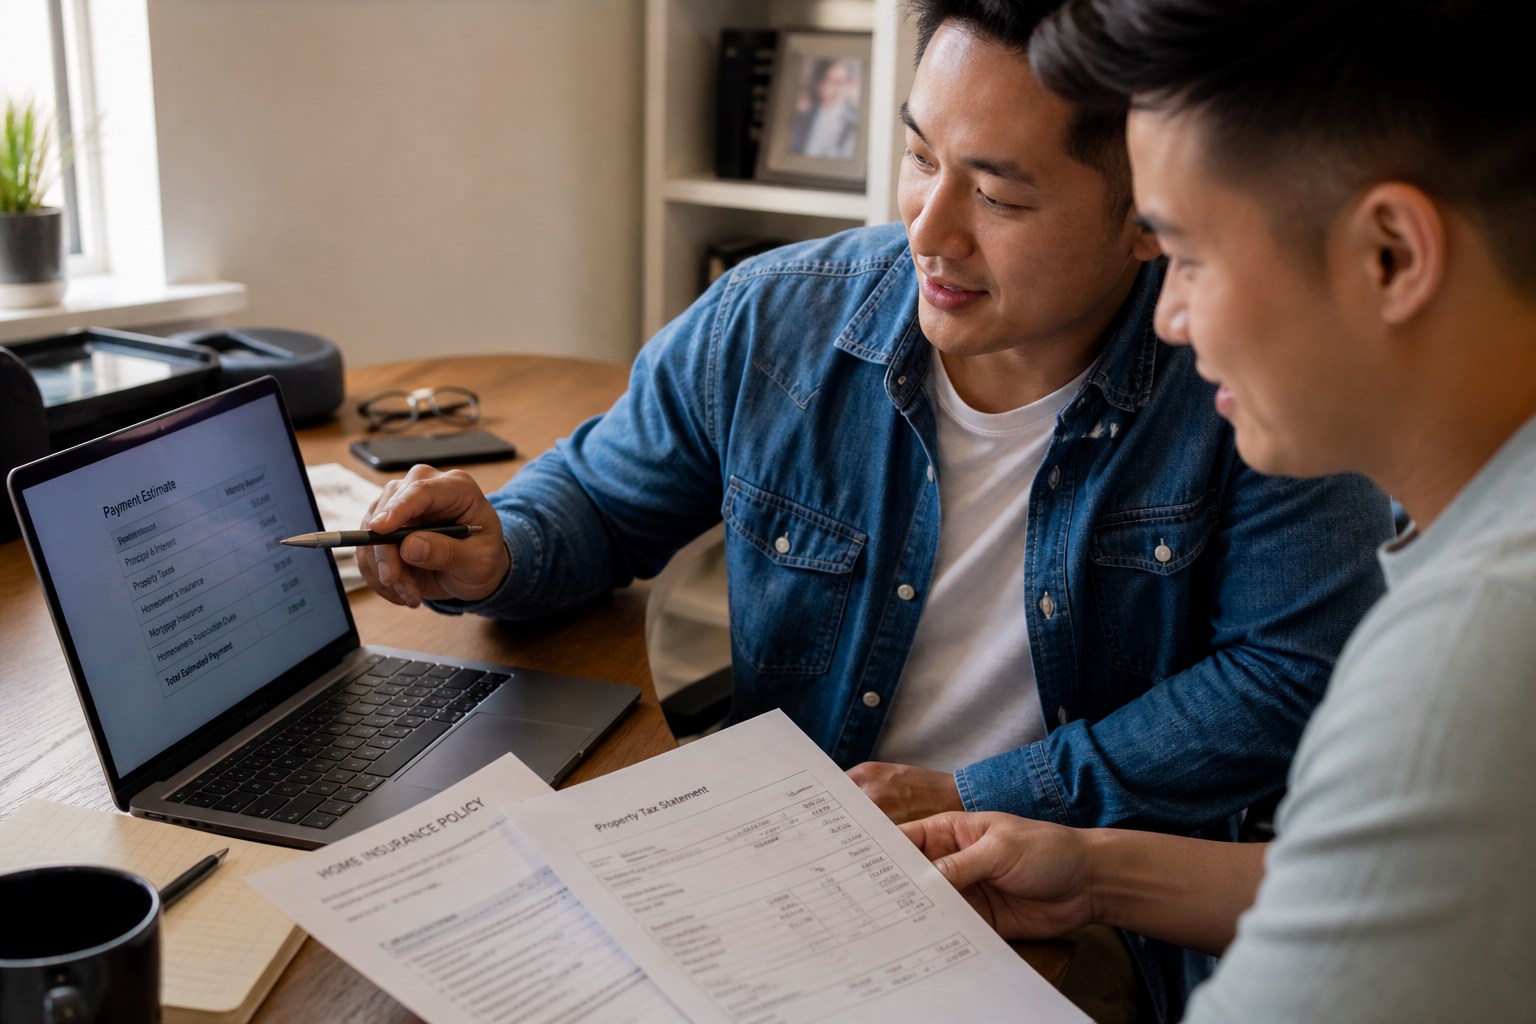
A VA loan payment includes more than principal and interest. Buyers should review the expected payment with property taxes, homeowners insurance, and any homeowner association dues. Depending on the transaction, other housing costs may also deserve attention. Looking only at a quoted interest rate can hide the budget question that matters most: Does this home payment fit comfortably within the household's broader financial picture?
Property costs can change from one home to another. A home with a lower purchase price may still carry higher recurring costs because of taxes, insurance, or association dues. A buyer moving from a rental may also need to plan for maintenance and utility changes. That small tangent is easy to overlook when the focus is on getting an offer accepted.
Use the current housing budget as a reference point
Start with current housing expenses and compare them with the estimated total payment for the proposed property. Then look at other obligations, savings goals, and expected changes in income or expenses. Underwriting will assess qualifying income and debt, while the buyer should assess whether the payment supports the life they want to live after closing.
Imagine two properties that both seem affordable based on principal and interest. One includes association dues and higher insurance costs. The second has lower ongoing property-related expenses. The complete payment review may show that the lower-priced home is not necessarily the lower monthly commitment.
A home loan consultation can help a buyer review estimated payments before they become emotionally committed to a particular property.
Understand how the VA funding fee may apply
The VA funding fee is a fee that may apply to a VA purchase or refinance loan. Its purpose is connected to the VA loan guaranty program. The amount and treatment of the fee can vary based on factors that include the type of loan use, down payment, and whether the borrower is exempt.
Eligible borrowers may be exempt from the VA funding fee. That status should be reviewed as part of the loan file rather than assumed. A lender can explain how the fee is reflected in the estimate for the particular transaction and whether it may be financed, subject to program requirements and loan terms.
For example, two eligible borrowers could review similar home purchases and receive different funding-fee outcomes because their VA loan histories or exemption status differ. The right question is not whether a funding fee always applies. The better question is how it applies to this borrower's proposed loan.
Buyers should also avoid treating the funding fee as the only closing cost to review. Closing expenses can vary by transaction, property, lender, and local requirements. A clear loan estimate discussion helps a buyer understand which costs are recurring, which are due at closing, and which may be negotiable through the purchase contract.
That is where a complete closing cost breakdown can be useful. It turns a broad program feature into a more practical conversation about the actual transaction.
Prepare for VA property and approval requirements
VA loans generally do not require monthly mortgage insurance, which may improve the monthly payment comparison for an eligible borrower. That feature does not replace the borrower qualification and property review required for approval. Income, credit, debts, assets, occupancy, appraisal results, and property condition can all affect the loan.
The VA appraisal considers value and includes a review tied to VA minimum property requirements. These standards are intended to help confirm the property is safe, sound, and sanitary. A home may be appealing to a buyer while still raising an appraisal-related concern that needs attention before closing.
Review the property before assuming the financing is settled
For example, a buyer may find a property that fits the budget and appears move-in ready during a showing. If the appraisal identifies a condition that must be addressed, the transaction may require additional discussion among the parties. That is why buyers, agents, and lenders benefit from involving the lender early when a property has visible condition concerns or an unusual property type.
A clean VA loan strategy brings the borrower's eligibility, estimated payment, funding-fee treatment, and property into the same conversation. It does not create a promise of approval. It gives the buyer a clearer basis for deciding whether to move forward.
Buying in Nevada or Oregon?
John Naccarato can help you understand VA financing requirements before you make an offer.
Loan eligibility and terms vary by borrower, property, lender, investor, and program guidelines. All loans are subject to approval. Equal Housing Lender.
Frequently Asked Questions
How do I confirm eligibility for VA loans before making an offer?
Request or review a Certificate of Eligibility with a VA-approved lender before making an offer. The COE helps establish eligibility and may provide entitlement information relevant to the loan review. The COE is not final loan approval. Income, credit, assets, debts, property requirements, and lender guidelines still apply.
What is included in a VA loan payment?
A VA loan payment generally includes principal, interest, property taxes, homeowners insurance, and applicable homeowner association dues. The estimated payment may also be affected by other transaction-specific costs. Reviewing the complete monthly housing cost gives a better budget picture than looking at the interest rate alone.
Do VA loans require monthly mortgage insurance?
VA loans generally do not require monthly mortgage insurance. This can be a meaningful difference when comparing financing options. VA loans may still include a funding fee unless the borrower qualifies for an exemption. Loan eligibility and terms vary.
Why does the VA funding fee vary?
The VA funding fee may vary based on factors such as loan use, down payment, and exemption status. Eligible borrowers may be exempt from the fee. A lender can explain how the funding fee applies to a specific purchase or refinance scenario and how it is reflected in the loan estimate.
Can a VA appraisal affect a home purchase?
Yes. A VA appraisal assesses property value and considers minimum property requirements. If the appraiser identifies a concern related to those requirements, the parties may need to address it before the loan can close. Appraisal outcomes depend on the property and the specific transaction. They should not be assumed in advance.
More Mortgage Guides
Subscribe to my newsletter
Get the latest Las Vegas real estate market updates, mortgage tips, and rate alerts delivered to your inbox.