Mortgage Tips: Where Your Money Should Go
The interest rate quietly shapes whether extra cash should pay down your loan or stay invested. Learn how to compare mortgage payoff against investing with a clear strategy.
The number quietly shaping your financial decisions
$1 growing into something much larger sounds like an investing headline, yet the same math influences mortgage decisions every day. One number, the interest rate, often determines whether extra cash should go toward paying down a loan or staying invested elsewhere.
Many buyers focus on monthly payment alone. That matters, though it does not tell the full story. The rate attached to a mortgage becomes the baseline for comparing other uses of money.
In simple terms, if funds can reasonably earn more than the cost of borrowing, some homeowners consider investing the difference. If not, reducing debt may offer a more predictable outcome. This idea shows up frequently in mortgage tips because it affects long term wealth building.
A borrower comparing options through a home loan consultation often finds that small differences in rate assumptions can shift the decision entirely.
Understanding compounding and why it matters for homeowners
Compounding allows money to grow over time as returns build on prior gains. This concept is often highlighted in investing, though it also applies in reverse with interest paid on debt.
Mortgage interest typically does not compound in the same way as an investment account. Still, the total cost of borrowing over time can be significant, especially when balances are high early in the loan term.
How this shows up in real scenarios
Consider a homeowner deciding between making extra payments or contributing to an investment account. If the investment grows steadily over time, compounding can accelerate results. If returns are inconsistent, the benefit becomes less certain.
This is why mortgage tips often stress evaluating both sides carefully. Paying down a loan delivers a guaranteed reduction in interest owed. Investing introduces variability, even if long term averages appear favorable.
Guidance from sources like the Federal Reserve highlights how interest rates influence borrowing behavior and household decisions. Federal Reserve data can help frame broader trends, though personal strategy should remain individualized.
Mortgage interest rate vs investment return
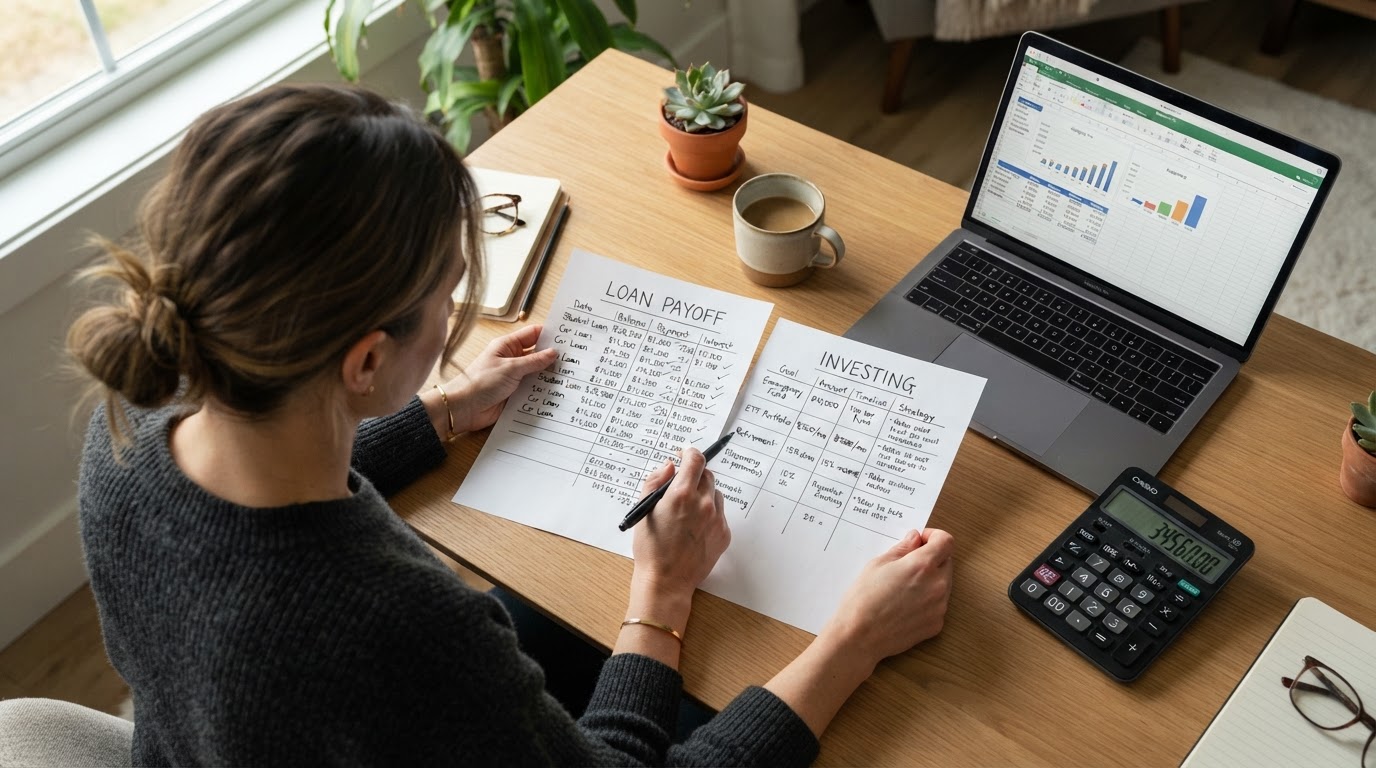
The comparison between a mortgage rate and potential investment return is one of the most common decision points for homeowners. This is where many mortgage tips become practical rather than theoretical.
If a mortgage carries a relatively higher rate, reducing that balance may provide a stronger financial outcome than seeking uncertain returns elsewhere. If the rate is lower, some borrowers choose to keep liquidity and invest.
A practical example
A borrower with a fixed rate loan evaluates whether to make additional principal payments. At the same time, they have access to retirement or brokerage accounts with historical returns that fluctuate over time.
The decision often comes down to risk tolerance. Mortgage payoff offers certainty. Investments offer potential growth with variability.
Data from sources like the Mortgage Bankers Association and long term housing research from Fannie Mae can provide context for how rates and borrowing costs behave over time. Still, personal cash flow and goals matter more than averages.
Liquidity, flexibility, and real life planning
Numbers alone do not make the decision. Access to cash plays a major role. Once money is used to pay down a mortgage, it is no longer easily accessible unless a borrower uses tools like a cash out refinance or HELOC.
Maintaining liquidity can provide flexibility for unexpected expenses, job changes, or future investments. This is especially relevant for self employed borrowers or those with variable income.
How borrowers approach this
- Some prioritize a strong cash reserve before making extra payments
- Others split funds between investing and loan reduction
- Many revisit the decision as rates or income change
A homeowner exploring options through a mortgage strategy session may find that flexibility is just as important as long term projections.
Guidance from the Consumer Financial Protection Bureau emphasizes the importance of emergency savings alongside debt management. CFPB resources can help frame responsible planning.
How this applies to homebuyers today
For buyers entering the market, this concept starts before closing. The structure of a loan, including rate type and term, affects how future decisions will play out.
Choosing between fixed and adjustable rates, evaluating loan programs, and understanding total cost all tie back to how money can work over time.
Example from a purchase scenario
A first time buyer compares two loan options with different structures. One offers payment stability. The other may start lower but adjust later. The choice impacts not only monthly affordability but also how extra funds might be allocated in the future.
Mortgage tips in this stage focus on clarity. Buyers benefit from understanding how each option fits into their broader financial plan rather than focusing only on immediate savings.
Data from the National Association of Realtors shows that financing structure plays a key role in long term homeowner satisfaction. NAR research supports the value of informed decision making.
A balanced approach to deciding where money should go
No single strategy fits every borrower. The most effective approach often blends multiple priorities, including debt reduction, investing, and maintaining liquidity.
Mortgage tips frequently point toward alignment with personal goals. Someone focused on stability may prioritize paying down debt. Another borrower focused on growth may allocate more toward investments.
Short term needs, long term plans, and comfort with risk all influence the outcome. Even small adjustments over time can shift results in meaningful ways.
Working through these decisions with clear information helps avoid reactive choices. A structured plan tends to outperform guesswork, even if adjustments are made along the way.
Want help deciding where your money should go?
Contact John Naccarato to compare your mortgage rate against your other financial options and build a strategy that fits your goals.
All loans are subject to approval. Equal Housing Lender. Loan eligibility, terms, and pricing vary by borrower, property, lender, investor, and program guidelines. This article is for educational purposes and is not investment or tax advice.
Frequently Asked Questions
Should I pay off my mortgage early or invest instead?
It depends on your mortgage rate, the returns you can reasonably expect from investing, your risk tolerance, and your need for liquidity. If your rate is higher than what you could reliably earn after taxes, paying down the loan may offer a more predictable outcome. If your rate is lower and you are comfortable with variability, investing the difference can make sense. There is no universal answer, which is why most mortgage tips frame this as a personal decision based on your full financial picture rather than a rule.
How does my mortgage interest rate affect financial decisions?
Your mortgage rate becomes the baseline for comparing other uses of money. If funds can reasonably earn more than the cost of borrowing after accounting for taxes and risk, some homeowners keep liquidity and invest. If not, reducing the loan balance offers a guaranteed reduction in interest owed. The rate does not make the decision for you, but it sets the hurdle that every other option has to clear.
Is it better to make extra mortgage payments or keep cash?
Keeping cash preserves liquidity for emergencies, job changes, or future opportunities, while extra payments lock your money into home equity that is harder to access without a refinance or HELOC. A balanced approach often works well: build a reserve first, then decide how much extra to direct toward the loan versus investing based on your rate and comfort with risk.
Do all loans allow extra payments without penalty?
Most modern fixed-rate loans allow extra principal payments without a penalty, but some loans include prepayment penalties or restrictions. Confirm the terms of your specific loan before committing extra funds. If a penalty applies, the math can change, so read your note carefully or ask your loan officer to confirm before making extra payments.
How can I decide the best mortgage strategy for my situation?
Start by clarifying your goals: stability, growth, or liquidity. Compare your mortgage rate against realistic after-tax investment returns, weigh your risk tolerance, and consider how accessible your cash needs to be. A structured plan with clear information tends to outperform guesswork. Reviewing the full picture with a loan officer through a home loan consultation can help align the strategy with your long term plans.
More Mortgage Guides
Subscribe to my newsletter
Get the latest Las Vegas real estate market updates, mortgage tips, and rate alerts delivered to your inbox.