Mortgage Denial Second Opinion: What to Do Next
A mortgage denial is not always final. Learn how a second opinion can reopen your file, why lenders differ, and the steps to take before you reapply.
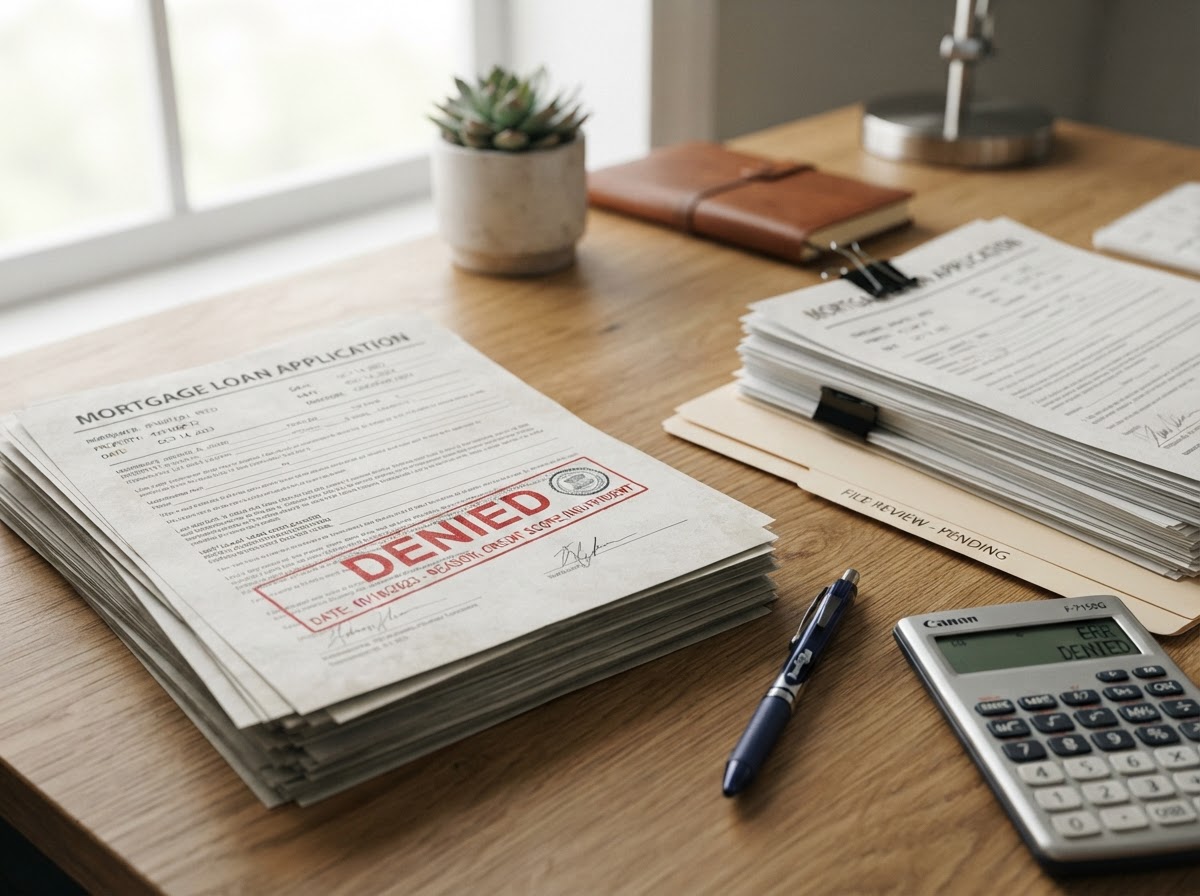
Mortgage denial second opinion: why one no is not final
A declined loan file sitting on a desk often feels like the end of the road. In practice, a mortgage denial second opinion can reopen that file with a different outcome. Lending is not one size fits all. Each lender works with different guidelines, overlays, and interpretations of borrower profiles.
Borrowers are evaluated through a mix of credit, income, assets, and property factors. Small differences in how those are calculated can change the decision. One lender may view variable income conservatively, while another may have a program designed for that exact scenario.
Guidance from the Consumer Financial Protection Bureau confirms that lenders may apply standards differently within regulatory frameworks.
How a second opinion changes outcomes
Different underwriting approaches can lead to a different result:
- Income calculation methods vary, especially for self-employed borrowers
- Debt-to-income tolerance can differ within program guidelines
- Access to niche products like bank statement or DSCR loans
Consider a borrower with multiple income streams who was declined due to inconsistent documentation. A second lender may structure the file using a program tailored to non-traditional income, leading to approval.
Common reasons loans get denied and how they are reviewed
Understanding why a loan was declined is the first step before seeking a second opinion. Denials typically fall into a few categories, but each has nuance.
Credit profile issues
A lower credit score or recent negative events can trigger a denial. Some lenders offer programs with more flexible credit thresholds depending on compensating factors.
Income and employment challenges
Self-employed borrowers, commission-based income, or recent job changes often require deeper documentation. A different lender may interpret income stability differently.
Debt-to-income ratio limits
If monthly obligations appear too high relative to income, the loan may not meet guidelines. Another lender might restructure the file by adjusting qualifying income or considering alternative programs.
Property-related concerns
Certain property types or condition issues can limit eligibility. Some lenders have broader property acceptance criteria. A borrower denied due to variable overtime income may later be approved when another lender averages income over a longer period allowed by guidelines from Fannie Mae or Freddie Mac.
How lenders differ in loan programs and guidelines
The mortgage market includes a wide range of loan products beyond standard conventional options. This is where a mortgage denial second opinion becomes especially valuable.
Program diversity across lenders
Not all lenders offer the same products. Some specialize in government-backed loans, while others focus on non-qualified mortgage options.
- FHA and VA loans may allow more flexibility in credit and down payment
- Bank statement loans support self-employed income documentation
- DSCR loans evaluate investment property cash flow instead of personal income
A borrower denied on a conventional loan due to income documentation might qualify under a bank statement program. That shift alone can change the entire approval path. According to HUD, FHA loans are designed to expand access to homeownership with more flexible qualification standards.
Steps to take after a mortgage denial
A denial should trigger action, not withdrawal. A structured approach increases the chance of success with a second opinion.
Review the denial letter carefully
Lenders are required to provide reasons for denial. This document highlights exactly what needs to be addressed.
Gather updated documentation
Income records, asset statements, and explanations for credit events should be organized before submitting to another lender.
Seek a qualified second opinion
Working with a loan officer experienced in multiple loan types improves the chances of finding a solution. A borrower who corrects a documentation gap, such as missing business expense clarification, may see a different outcome when the file is resubmitted elsewhere.
Data from the Mortgage Bankers Association shows that underwriting standards can vary across institutions, reinforcing the value of exploring multiple options.
When a second opinion may not change the outcome
A mortgage denial second opinion is not a guarantee of approval. Some factors are consistent across all lenders.
Hard guideline limits
Certain thresholds, such as recent major credit events or insufficient income, may not meet minimum program requirements anywhere.
Insufficient assets
If funds for down payment or reserves are not available, options may be limited until financial conditions improve.
Unverifiable income
Income that cannot be documented to guideline standards typically cannot be used for qualification. Even in these cases, a second opinion can still provide a roadmap. A borrower may learn what steps are needed to qualify in the future, such as improving credit or stabilizing income.
Building a stronger file for the next approval
Preparation plays a central role in turning a denial into an approval. A strategic approach increases confidence for both borrower and lender.
Focus on financial positioning
Reducing outstanding debt or increasing reserves can improve loan eligibility.
Improve documentation clarity
Clear and consistent records help underwriters assess the file accurately.
Work with experienced professionals
A knowledgeable loan officer can identify the right program and structure the file appropriately from the start. A borrower who previously struggled with inconsistent income reporting may later qualify after organizing documentation and selecting a program aligned with their financial profile.
For additional planning guidance, review resources from the National Association of Realtors.
All loans are subject to approval. Equal Housing Lender.
Ready to get pre-qualified?
Contact John Naccarato at (702) 813-4632 or via email at john@johnnaccarato.com, or book a free consultation.
Contact me:
John Naccarato, RMLS# 2788373
Loan Officer, Intercap Lending
Las Vegas, Nevada
Equal Housing Lender
Frequently Asked Questions
Can I apply with another lender after being denied a mortgage?
Yes. A denial from one lender does not prevent you from applying elsewhere. Lenders work with different guidelines, overlays, and loan programs, so a file that did not fit one lender may qualify under another. Before reapplying, review the denial reasons, gather updated documentation, and consider working with a loan officer experienced in multiple loan types.
Will a second mortgage application hurt my credit?
Multiple mortgage applications within a short window are generally treated as a single inquiry for credit scoring purposes, so shopping for a second opinion typically has limited impact. It is still wise to confirm your credit position with the loan officer before applying and to avoid opening new credit accounts during the process.
How do I know why my loan was denied?
Lenders are required to provide the specific reasons for a denial, usually in a written notice. This document identifies the factors that drove the decision, such as credit, income, debt-to-income ratio, or property concerns. Reviewing it carefully is the first step before seeking a second opinion.
What is the most common reason for mortgage denial?
Debt-to-income ratio, credit history, and income documentation are among the most common reasons. Each has nuance, though. A lender may interpret variable income, recent job changes, or compensating factors differently, which is why the same file can produce a different outcome with another lender.
Is a mortgage denial final?
Not necessarily. A denial reflects one lender's review under one set of guidelines. A second opinion may reveal a different program or structure that fits the file. Even when a denial cannot be reversed immediately, a second opinion can clarify what steps are needed to qualify in the future.
More Mortgage Guides
Subscribe to my newsletter
Get the latest Las Vegas real estate market updates, mortgage tips, and rate alerts delivered to your inbox.