Mistakes When Buying a Home to Avoid
Many homebuyer regrets start before the first showing. Learn the most common mistakes when buying a home and how preparation, a full cost picture, and clear guidance help you avoid them.
Mistakes when buying a home often start before the search
A majority of homebuyers report at least one regret after closing, according to research from Zillow. Many of those regrets trace back to decisions made before touring a single property. The early stage is where financial positioning and expectations are set, and small missteps can carry through the entire transaction.
One common issue involves skipping a proper pre-approval. Buyers sometimes rely on rough online estimates instead of a verified review of income, assets, and credit. That creates uncertainty when it is time to make an offer.
Why pre-approval matters
- It establishes a realistic price range based on verified data
- It signals credibility to sellers in competitive markets
- It uncovers potential qualification issues early
Consider a buyer who starts shopping based on an online calculator, only to learn later that their debt-to-income ratio limits their options. That delay can mean missing out on homes or needing to adjust expectations mid-process. A structured pre-approval helps prevent that outcome.
Buyers looking to prepare properly can review guidance from the Consumer Financial Protection Bureau at consumerfinance.gov.
Overlooking total housing costs beyond the mortgage
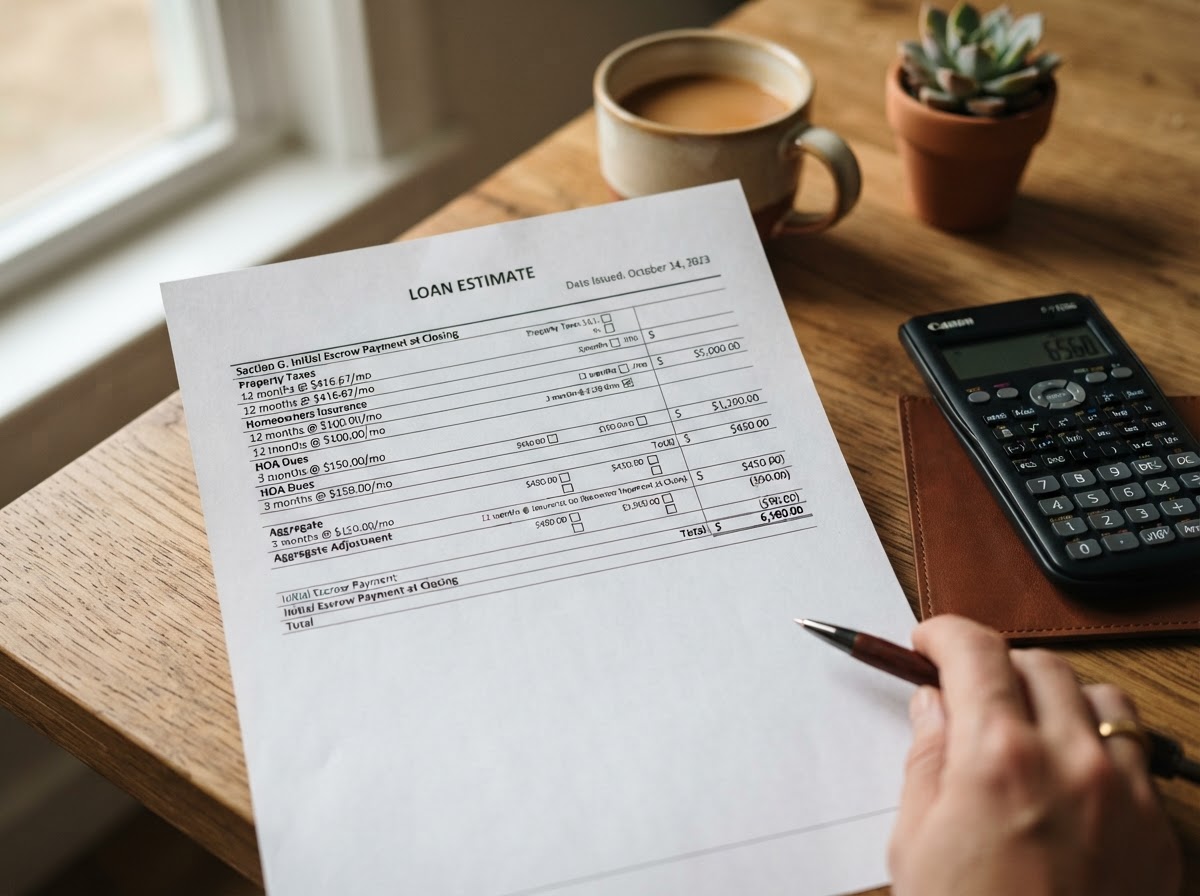
Focusing only on the monthly mortgage payment is one of the most common mistakes when buying a home. The full cost of ownership includes several additional factors that can shift affordability.
Property taxes, homeowners insurance, maintenance, and utilities all contribute to the real monthly obligation. These costs vary by location and property type, and they can change over time.
What buyers should factor in
- Escrow items such as taxes and insurance
- Ongoing maintenance and repairs
- HOA dues if applicable
For example, a buyer may qualify for a certain loan amount, but once taxes and insurance are added, the payment may exceed their comfort level. That difference often becomes clear only after a detailed loan estimate is reviewed.
Data from the U.S. Census Bureau shows that housing expenses extend well beyond principal and interest, reinforcing the need for a full financial picture before committing.
Credit and debt decisions during the process
Changes to credit or debt during the loan process can affect approval. This area creates risk for buyers who are unaware of how sensitive mortgage underwriting can be.
Opening new credit accounts, financing a vehicle, or missing payments can alter credit scores and debt ratios. Even small shifts may impact loan terms or eligibility.
Common actions to avoid
- Applying for new credit before closing
- Making large unexplained deposits
- Changing employment without consulting a lender
A buyer might assume that financing furniture before closing is harmless, only to find that the added debt changes their qualification. Communication with a loan officer before making financial moves is key.
Guidance from Fannie Mae emphasizes maintaining stable financial behavior from application through closing, which helps ensure consistent loan approval outcomes.
Skipping a clear financing strategy
Another frequent issue among mistakes when buying a home is choosing a loan product without understanding how it fits long-term goals. Different loan programs serve different needs, and the right option depends on income structure, time horizon, and risk tolerance.
Options such as FHA, VA, conventional, and non-QM loans each have distinct guidelines. Selecting one without context can lead to higher costs or limited flexibility later.
Example of strategy mismatch
A self-employed borrower might default to a conventional loan, only to struggle with income documentation. A bank statement loan could offer a more suitable path based on cash flow instead of tax returns.
Buyers benefit from reviewing multiple scenarios. This includes comparing down payment structures, mortgage insurance implications, and potential refinance strategies.
Freddie Mac provides educational resources at freddiemac.com that explain how different loan types function.
Letting emotion drive purchase decisions
Emotional decision-making can override sound financial judgment. This tends to happen in competitive markets where urgency and pressure are high.
Buyers may stretch beyond their intended budget or waive protections without fully understanding the consequences. While securing a home is important, maintaining financial stability after closing matters just as much.
How to stay grounded
- Set a firm budget before shopping
- Evaluate homes based on long-term suitability
- Consult with trusted professionals before making offers
Consider a scenario where a buyer increases their offer significantly to win a bidding situation, only to feel strain from the higher payment afterward. A structured approach helps balance competitiveness with financial responsibility.
The National Association of Realtors highlights that disciplined planning leads to better long-term satisfaction for homeowners.
Ignoring professional guidance and communication
Real estate transactions involve multiple parties, timelines, and regulatory requirements. Trying to manage everything without clear communication can lead to avoidable setbacks.
Working with experienced professionals provides clarity at each stage. Loan officers, agents, and other advisors help interpret requirements and keep the process on track.
Where communication makes a difference
- Understanding loan conditions and documentation needs
- Coordinating timelines between lender and agent
- Addressing issues before they delay closing
A buyer who delays responding to documentation requests may unintentionally slow underwriting. Staying engaged and responsive helps maintain momentum.
Those exploring the process further may benefit from resources like home loan consultation guidance and mortgage pre-approval planning to build a clear path forward.
Want to avoid the common pitfalls?
Contact John Naccarato to get pre-approved, compare loan options, and build a financing plan that keeps you grounded before you make an offer.
All loans are subject to approval. Equal Housing Lender. Loan eligibility, terms, and pricing vary by borrower, property, lender, investor, and program guidelines. This article is for educational purposes only.
Frequently Asked Questions
What are the biggest mistakes when buying a home for the first time?
The most common first-time buyer mistakes are skipping a verified pre-approval, focusing only on the mortgage payment instead of total housing costs, making credit or debt changes mid-process, choosing a loan without understanding how it fits long-term goals, letting emotion drive the offer, and avoiding clear communication with the professionals on the transaction. Addressing these early keeps the process on track and reduces regret after closing.
How does pre-approval help avoid home buying mistakes?
A verified pre-approval establishes a realistic price range based on reviewed income, credit, and assets. It uncovers potential qualification issues early, signals credibility to sellers in competitive markets, and prevents the disappointment of finding a home you cannot finance. Starting with a rough online estimate instead often creates uncertainty exactly when a strong, timely offer matters most.
Can opening new credit affect a mortgage approval?
Yes. Opening new credit accounts, financing a vehicle, making large unexplained deposits, or changing employment during the loan process can alter your credit score and debt ratios, which may affect loan terms or eligibility. The safest approach is to keep your financial profile stable from application through closing and to consult your loan officer before any significant financial move.
Why is it important to understand total homeownership costs?
The mortgage payment is only part of the picture. Property taxes, homeowners insurance, maintenance, utilities, and HOA dues all contribute to the real monthly obligation, and these costs vary by location and property type. Qualifying for a loan amount does not guarantee the total payment fits your budget, which is why reviewing a full loan estimate before committing matters.
What loan options should buyers compare?
Buyers should compare FHA, VA, conventional, and non-QM options based on income structure, down payment, mortgage insurance implications, time horizon, and risk tolerance. A self-employed borrower, for example, may benefit from a bank statement loan rather than defaulting to conventional. Comparing multiple scenarios rather than choosing the first product presented helps align the loan with long-term goals.
More Mortgage Guides
Subscribe to my newsletter
Get the latest Las Vegas real estate market updates, mortgage tips, and rate alerts delivered to your inbox.